Technology platforms such as Payneteasy help businesses manage global payouts through integrated banks and payment providers. They let businesses send money to contractors, vendors, policyholders, or customers securely and reliably, without the usual back-and-forth. When payments are simpler, businesses don’t have to worry so much about mistakes1 and can actually focus on the work that keeps them moving forward.
Payneteasy provides a payout API for submitting instructions to integrated payment providers, with configurable routing, approval workflows, status tracking and reporting. Available methods and currencies depend on the connected provider and corridor. Payneteasy does not hold or move funds; settlement remains with the licensed banking and payment partners. Confirm which provider statuses indicate processing, completion or beneficiary credit.
Here’s what the whole process looks like.
What Are Global Payouts?
Global payouts are the systems businesses use to send money to people or partners across borders. Instead of relying on slow bank transfers or manual workarounds, these platforms let a company in London pay a contractor in Nairobi, a driver in Warsaw, or a supplier in Manila with much less friction. Payouts can land in a bank account, on a card or in a digital wallet, in the recipient’s local currency.
How to Send International Payouts: Step-by-Step
Whether you pay ten contractors or ten thousand sellers, cross-border payouts follow the same sequence. The steps below cover the full flow, from choosing a provider to closing the books.
1. Choose a Payout Provider
Start with the corridors you need today and the ones you plan to open next. A global payouts platform should cover your recipients’ countries and local currencies, support multiple payment methods (bank transfers, card payouts, e-wallets) and expose a payout API, so payouts run from your own system rather than a bank portal. Compare the total cost, not only the headline fee: FX margin, intermediary charges and the handling of failed payments often decide whether a provider is cost effective at your volume.
2. Complete KYC and Onboard Beneficiaries
Complete business onboarding with your bank or regulated payment provider, including KYB where required. Then collect the beneficiary information needed for each payout method and corridor using approved collection methods, such as a hosted form or the API. KYC and identity verification requirements depend on the jurisdiction, the transaction and the provider. Keep beneficiary details up to date and validate them to reduce avoidable payout rejections.
3. Fund Your Payout Balance
Payouts are sent from a pre-funded balance held with the bank or licensed payment institution behind your setup. Most global businesses keep balances in their main currencies, such as USD, EUR and GBP, and top them up by bank transfer ahead of each payout run. Forecast the payroll, invoices and contractor payments due in the cycle, so a batch never stalls on an empty balance.
4. Upload the Batch or Call the Payout API
Smaller teams usually start with batch uploads: a CSV file listing the beneficiary, amount, currency and payment reference. As volume grows, payout automation through the API takes over, and your platform creates batch payments when an order clears, an invoice is approved or a pay period closes. Validation at this step (IBAN format, account number checks, duplicate detection) reduces errors before any money moves.
5. Currency Conversion (FX) and Routing
Each payment is converted into the beneficiary’s currency and sent over the most suitable payment rails. A euro payment to Germany can go over SEPA, a dollar payment to a US supplier over ACH, and a payment to a corridor without a local scheme over SWIFT. Routing weighs cost, speed and the recipient’s preferred method, while FX conversion at competitive exchange rates keeps the sender’s cost predictable.
6. Track Delivery and Settlement
Delivery time depends on the payment method, provider, destination and any compliance checks. Eligible SEPA Instant payments make funds available within ten seconds. UK Faster Payments are usually available almost immediately but can take up to two hours. ACH credits can settle on the same banking day, the next banking day or within two banking days. For international wires, confirm the provider’s delivery estimate. An accepted payout instruction does not confirm beneficiary credit, and interbank settlement may occur separately from funds becoming available to the recipient.
7. Reconciliation
The last step is matching every payout to your ledger: amount sent, FX rate applied, fees charged and final status. Automated reconciliation through API callbacks and daily settlement reports closes this loop without spreadsheets. Returned payments, for example to a closed account, come back into the same report, so finance can correct the beneficiary’s details and resend. More on this in our article on multi-currency clearing and real-time reporting.
Payneteasy connects payout processing, routing and reporting through one API. Share your corridors and volumes, and we will show how the setup would look for your business.
Talk to our teamHow Global Payout Platforms Work
Most global payout platforms offer an API that a company can plug into its own system. For example, a marketplace can set up automatic payouts to thousands of sellers at once instead of uploading spreadsheets or logging into a bank portal every time.
The platform decides how to send the funds. A transfer from London to Berlin may go through SEPA in euros on the same day, and a payment to India may go through Swift or a local partner bank. These routes, called payout corridors, are there to match each payment with the fastest and most cost-effective option.
One file can also mix payout types — mass payments to freelancers and wire transfers to suppliers — so a business paying suppliers and staff on the same day can manage multiple recipients across different corridors in one batch.
Before a recipient sees the money, the platform requires bank account checks or ID verification to meet rules on fraud prevention and compliance with KYC or AML laws2. Some services let recipients create a profile once and use it again with different payers, which saves time for both sides.
The platform also checks sanctions lists, flags unusual transfers, and applies foreign exchange rates where needed.
Main Benefits of Using a Global Payout Solution
Here are the key benefits of handling international payments through one simple system:
| Benefit | What It Means |
|---|
| Faster Cross-Border Payments | Money no longer crawls through the banking system for days. Funds can reach an account in India in under a minute or arrive in Brazil the same day by tapping into local rails instead of long routes. |
| Lower Costs with Transparent FX Fees | Traditional banks layer charges at every step, and the final amount can be less than expected once it reaches the recipient. Modern payout systems show the exchange rate up front and remove most of the intermediary fees. |
| Compliance Workflow Support | Payout tools can support beneficiary data collection, review workflows and audit records. Confirm which organisation performs KYC, sanctions screening, transaction monitoring and any required regulatory reporting. Automation does not remove the responsible organisation’s compliance obligations. |
| Real-Time API Integrations | Instead of uploading spreadsheets or chasing manual approvals, businesses can link a payout API directly into their finance tools. For example, a business can set global marketplace payouts to run once an order clears, or a staffing platform can pay workers as soon as hours are approved. The status of every transfer is available immediately through the same link. |
| Improved Recipient Experience | For the person on the other side, the way the money arrives matters. Global payout platforms provide this flexibility, and when money arrives quickly and in the right format, trust in the business grows. |
Key Use Cases for Global Mass Payouts
Businesses use global payouts to pay international contractors, marketplace sellers and partners as they expand into new markets.
Marketplaces rely on clear, reliable payouts to keep sellers on board. Remote teams expect their pay to land directly in their local accounts rather than going through slow international systems. Gig platforms get judged by how quickly freelancers get their funds. Even established exporters now feel the push to settle bills in local currencies if they want to stay competitive.
Some payment challenges only become obvious when money has to reach many people at once. That’s where mass payouts prove their worth.
- Marketplaces: think about platforms like Etsy or Upwork. Every week, they need to get money to thousands of sellers and freelancers around the world. Mass payouts make sure funds reach accounts quickly, so sellers can focus on their work instead of waiting for payments to clear.
- Gig Platforms: services like Uber and Fiverr rely on paying workers in multiple countries. Timely, predictable payments help drivers and freelancers trust the platform and keep doing their jobs.
- Affiliate Networks: Amazon Associates, Rakuten, or Impact need to pay commissions to affiliates around the world. Mass payouts let them settle dozens or even hundreds of accounts at once.
- Freelancers and Content Creators: Patreon, Substack, and Canva pay creators like writers, designers, and video producers directly. Creators can choose to receive funds to a bank account, card, or digital wallet.
- SaaS Companies with Global Contractors: SaaS companies, such as Shopify and Slack, collaborate with developers and consultants across multiple countries. Similar to other industries, they rely on mass payouts to handle payments efficiently.
How to Choose the Right Global Payout Platform
The platform you choose will determine how secure your transactions are, how transparent the costs look, and how well the system supports your business as it grows.
| What to Check | Why It Matters |
|---|
| Geographic and Currency Coverage | Check that the platform supports the countries and regions where your recipients are located. If you work with contractors, sellers, or affiliates across multiple currencies, make sure the system can send and receive funds in the ones they use. You may also want to consider countries and currencies you might need in the future. |
| Speed and Reliability | Look at how quickly payments reach recipients and how often the system experiences downtime. Some global payout solutions offer fallback routes or alternative payment rails to keep transfers moving even when one network slows or fails, often powered by a
payment orchestration platform. |
| Fees and Transparency | Costs should be predictable. Confirm how the platform charges for transactions, withdrawals, and foreign exchange. Hidden fees or fluctuating FX rates can quietly erode payouts and frustrate recipients. |
| API and Integration Options | Review the developer tools and integration options. Strong API documentation, SDKs, and plug-and-play connections make it easier to automate payouts and link the platform to your existing finance or ERP systems. |
| Support and Dispute Resolution | Check how the platform handles onboarding, answers questions, and resolves payment issues. When problems arise, you want a system that responds quickly and keeps payouts on track. |
Payment Methods for Global Payouts
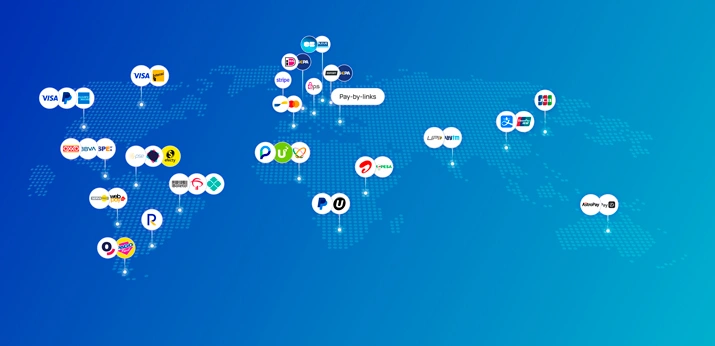
At this point, it’s worth looking at the payout methods businesses rely on today, as well as the newer ones gaining ground.
The right payout method depends on the country, the currency and how fast the recipient expects the money. The table below compares the main options; coverage and timing vary by provider and corridor, so confirm them before go-live.
| Payout method | Payment rails | Where it is used (currency) | Typical settlement time |
|---|
| Local bank transfer (Europe) | SEPA Credit Transfer, SEPA Instant | EU/EEA, UK, Switzerland and other SEPA countries (EUR) | Seconds (SEPA Instant) to 1 business day |
| Local bank transfer (UK) | Faster Payments, Bacs | United Kingdom (GBP) | Usually minutes (Faster Payments); 3 business days (Bacs) |
| Local bank transfer (US) | ACH, Same Day ACH | United States (USD) | Same day to 2 business days |
| International wire | SWIFT | 200+ countries and territories (most currencies) | 1–5 business days |
| Instant local rails | PIX, UPI, SPEI | Brazil (BRL), India (INR), Mexico (MXN) | Seconds to minutes |
| Card payouts | Push-to-card (Visa Direct, Mastercard Move) | Eligible debit cards in many markets (card currency) | Often within minutes |
| E-wallets and mobile money | PayPal, M-Pesa, GCash, Alipay | Global wallets; Kenya (KES), Philippines (PHP), China (CNY) | Usually near-instant |
Three of these groups are worth a closer look.
Swift Transfers
The Swift network is the traditional method for cross-border bank transfers.
- Global reach, connects thousands of banks worldwide
- Trusted and secure system
- Can take several days to complete
- Expensive due to bank fees and intermediary costs
Digital Wallets, Mobile Money, and Cross-Border Payment Platforms
Digital wallets, mobile money services, and cross-border payment platforms offer fast alternatives to traditional methods, especially in regions with limited banking infrastructure.
- Fast, often instant transfers
- Accessible in regions with limited traditional banking
- Convenient for recipients without a bank account
- Limited to certain countries or platforms
- Fees vary depending on the provider and currency
Examples and popularity:
- Payoneer: widely used by freelancers and marketplaces globally
- PayPal: common for small international transfers, especially in the US and Europe
- Alipay: popular in China for payments to consumers and businesses
- M-Pesa: common in Kenya and parts of Africa for mobile-based transfers
- GCash: widely used in the Philippines for mobile payouts and peer-to-peer transfers
Prepaid Cards
Virtual and physical prepaid cards provide recipients with instant access to funds without a bank account.
- Instant access to funds without a bank account
- Flexible for spending in multiple currencies
- Useful in regions where bank transfers are slow
- May carry activation or maintenance fees
- Limited in where they can be used or withdrawn
Fees and FX Costs
The fee on the invoice is rarely the full cost of an international payment. The total is made up of several layers, and each one behaves differently depending on the method.
| Cost component | What it is | How to keep it down |
|---|
| Payout fee | A flat or percentage fee per transfer charged by the provider | Negotiate volume tiers and group payments into batches |
| FX margin | The difference between the rate you get and the mid-market rate | Compare quotes with the mid-market rate and lock rates for scheduled payouts |
| Intermediary bank fees | Deductions by correspondent banks along a SWIFT wire | Use local rails where they exist; choose the OUR charge option when the beneficiary must receive the full amount |
| Receiving bank fees | Charges by the beneficiary’s bank for incoming international transfers | Pay out in local currency over domestic rails |
| Failed and returned payouts | Return fees plus staff time when details are wrong | Validate bank details and IBANs before sending |
| Method | Per-payout fee | FX cost | Intermediary fees |
|---|
| SWIFT wire | Higher, usually flat per wire | Set by the sending bank, often a wider margin | Possible, one or more correspondent banks |
| Local bank transfer | Low | Set by the payout provider | None |
| Card payouts | Moderate | Card network or provider rate | None |
| E-wallets and mobile money | Varies by wallet | Wallet or provider rate | None |
Traditional bank transfers over SWIFT remain the fallback for corridors without a local scheme and for high-value payments. For regular mass payments, local rails combined with competitive FX rates are usually the more cost effective route.
Compliance and Regulations: AML, KYC and Sanctions
Cross-border payout requirements depend on the jurisdictions, payment method and roles of the organisations involved. Agree which parties are responsible for customer due diligence, transaction monitoring, sanctions controls and record keeping. For a payout program, that usually comes down to three controls.
- KYC and KYB: apply customer due diligence where required and collect the beneficiary information needed for the payout. Verification and enhanced due diligence requirements depend on applicable rules and risk. Keep the required information up to date.
- AML transaction monitoring: watch for patterns that do not fit the beneficiary’s profile, such as sudden volume spikes, payments split just below thresholds or repeated changes of bank details, and escalate them for review.
- Sanctions screening: screen the relevant parties against sanctions lists applicable to the jurisdictions and organisations involved. Establish procedures for reviewing potential matches and re-screening when applicable lists or party details change.
Record keeping matters as much as the checks themselves. Under the UK Money Laundering Regulations, covered businesses generally retain relevant records for five years after the business relationship ends or the occasional transaction is completed, subject to applicable exceptions. EU Regulation 2023/1113 specifies the information required to accompany covered transfers, with different provisions depending on the transfer.
Payneteasy is a technology platform, not a bank, and does not hold or move funds. It supports configurable payout holds, approval workflows and reporting. The regulated providers and other responsible organisations retain their applicable KYC, AML and sanctions obligations. For the wider risk picture, see our overview of payment risks and compliance.
How to Integrate a Global Payout API Into Your Business
A payout API takes effort to set up, but the steps are clear. Once security, payouts, and tracking are in place, it works as part of your system.
- API Authentication and Access: most platforms provide API keys, OAuth tokens, or certificates to confirm your system’s identity. Assign roles carefully so only authorised team members can send payments or access sensitive data.
- Currency Handling and Conversion: some platforms let you lock in rates for scheduled payouts or batches, which keeps the amount your recipients receive consistent and helps you get the maximum value from each transfer. Plan ahead for the currencies you use most to avoid unexpected losses.
- Compliance and KYC Integration: take advantage of the tools your provider offers to handle KYC and AML requirements. Gather the necessary information from recipients, verify their identities, and keep records in secure storage. You can do this through an API or dashboard to avoid mistakes.
Common Challenges in Global Payouts and How to Solve Them
Modern global payout systems solve most cross-border payment problems, but a few tricky issues still pop up that businesses need to watch out for.
- FX Volatility Currency values can change between the moment you send funds and when recipients receive them. You can manage this by locking exchange rates for scheduled payouts or using forward contracts to protect payments from sudden swings.
- Regulatory Compliance Each country has its own rules for cross-border payments, which can affect how and where you send money. Platforms that track local laws and alert you to restricted transactions can prevent mistakes and failed transfers.
- Country-Specific Restrictions Some regions limit which payout methods you can use or require additional reporting. Certain transfers to high-risk jurisdictions3 may be blocked or require extra approvals. To avoid this, check supported countries and payment options before sending funds.
- Fraud Prevention and KYC Payments can be intercepted or sent to the wrong person if identities aren’t checked. You can prevent this by confirming recipient information and watching for unusual activity before sending funds.
- Failed and Returned Payouts Wrong account numbers, closed accounts or name mismatches send money back days later, often minus fees. Validate bank details at onboarding, use automated reconciliation to catch returns quickly, and let beneficiaries update their own details.
Why Global Payouts Are the Future of Scalable Businesses
Not long ago, sending money across borders meant delays, high fees, and little clarity on the financial status of payments. That picture is changing quickly.
The next stage looks even more promising. International bodies including the G20 are targeting a global average cost of no more than 1% for retail cross-border payments, with no corridor exceeding 3% by the end of 20274, while EU instant euro payment obligations are being introduced in stages, with deadlines depending on the provider’s location and type5. At the same time, smarter use of local payment systems will help international transfers feel less complicated and almost as easy as sending money at home.
The future of cross-border payouts could soon look a lot like domestic transfers.
Sources
[1] - EY, The rise of PayTech - seven forces shaping the future of payments, November 2022
[2] - GOV.UK, Your responsibilities under money laundering supervision, May 2025
[3] - The FATF, High-Risk Jurisdictions subject to a Call for Action, June 2025
[4] - Financial Stability Board, G20 Roadmap for Enhancing Cross-Border Payments: Consolidated progress report for 2023, October 2023 (targets set for 2027)
[5] - European Commission, Instant Payments Regulation (EU) 2024/886, April 2024
Contact author